The Urban Redevelopment Authority (URA) released its final private property figures for the third quarter of 2026 on 23 October. Island-wide, prices rose faster than in any quarter this year. In the Core Central Region (CCR), where Bukit Timah and Turf City sit, the picture was much quieter: prices barely moved, rents slipped and vacancy edged up.
Here is what the numbers say, how property consultants read them, and what they mean if you are weighing a home in Bukit Timah, including Dunearn House.
The headline numbers
URA's overall private residential price index rose 1.4% in Q3 2026, up from 0.5% in Q2. Over the first three quarters, prices rose an average of 0.9% a quarter. Landed homes did most of the lifting at 2.9%, while non-landed homes rose 1.0%.
Broken down by region, the gap is clear:
| Non-landed homes | Price change Q3 2026 | Price change Q2 2026 | Rental change Q3 2026 | Vacancy, end Q3 2026 |
|---|---|---|---|---|
| Core Central Region (CCR) | +0.3% | +1.8% | -0.3% | 8.4% |
| Rest of Central Region (RCR) | 0.0% | -1.2% | +1.5% | 7.4% |
| Outside Central Region (OCR) | +2.3% | -0.1% | +3.1% | 6.5% |
So the suburbs led the quarter, while the prime districts held roughly flat after a strong second quarter.
Flash versus final: why CCR "fell" and then "rose"
If you read the early October headlines, you may have seen that CCR prices dipped. That came from URA's flash estimate, which is based on data up to mid-quarter. ERA Singapore's research team, Elizabeth Choong and Ethan Hariyono, wrote on 2 October that the CCR was "the only market segment which saw a dip in prices, inching down 0.1% q-o-q", and put it down to the high base set in Q2.
The final URA figures, which include the full quarter's transactions, turned that into a 0.3% rise. Either way, the message is the same: prime-district prices moved sideways in Q3, rather than falling or jumping.
A quiet quarter for new launches
Developers launched 1,140 new private homes (excluding ECs) in Q3, down from 1,783 in Q2, and sold 1,183, down from 2,141. Resales made up 73.9% of all private home sales, up from 62.0%.
ERA counted only three new launches in the quarter: Lentor Gardens Residences in the OCR, and Dunearn House and Amberwood At Holland in the CCR. It reported launch-weekend take-up of 56% at Dunearn House and 11% at Amberwood At Holland, and noted the two were the first launches in the new Bukit Timah Turf City and Holland Plain estates. You can see how the other District 10 launches around Holland and Tanglin compare.
Xian Wong of Cushman & Wakefield said new sales volume fell 44.7% quarter-on-quarter, the steepest drop of any sale type. "While private residential prices continue to rise, buyers have become more cautious amid ongoing macroeconomic uncertainty," the firm wrote, adding that with sellers holding firm on prices, "transaction volumes may stay tempered even as prices continue to edge up."
What analysts expect next
- Prices: Cushman & Wakefield said Q3 was the eighth straight quarter of rising prices, with a 2.8% gain so far in 2026, and expects 3.0% to 4.0% for the full year. ERA said prices remain on track for its 3% to 5% forecast.
- CCR supply: ERA counted about 1,424 CCR units launched in 2026 and expects no further CCR projects this year. It said buyers looking for new CCR homes may have to wait until 2027, when projects in Newton and Turf City could launch.
- Rents: Cushman & Wakefield expects island-wide rents to grow up to 3.0% in 2026, but noted that high-end CCR rents fell 0.3% in Q3 while OCR and RCR rents rose.
- Upgraders: Cushman & Wakefield noted that HDB resale prices fell 0.1% in Q3, a third straight quarterly decline, and said upgrader momentum could slow even though demand is expected to persist.
- Land prices: developers are still bidding firmly for well-located sites. Cushman & Wakefield pointed to the Lorong Puntong / Sin Ming Avenue GLS site, sold in September at S$1,612 psf ppr, a record for a residential site in the RCR.
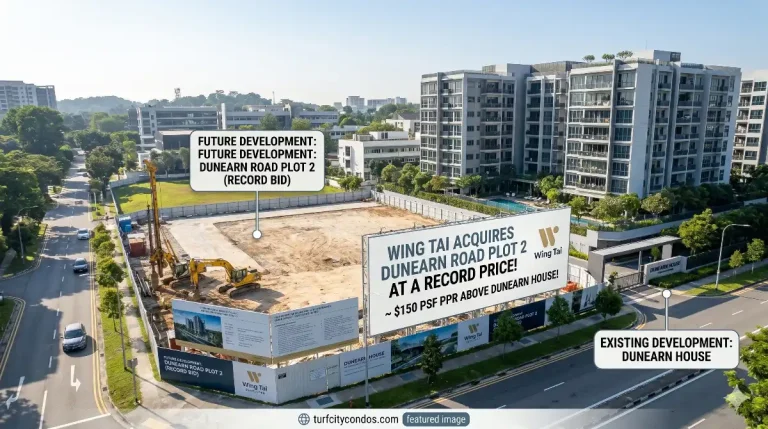
Over the longer run, URA says about 32,800 private homes, including ECs, could be made available for sale in the next one to two years, including about 4,745 units from the second-half 2026 GLS Confirmed List. For context on how land prices around Turf City have moved, see our look at Wing Tai's record Turf City bid and what the Peck Hay Road tender means for Dunearn House buyers.
What it means if you are buying in Bukit Timah
A few practical takeaways from the data, depending on why you are buying:
- Own-stay families and right-sizers: a flat quarter in the CCR is not a sign of weakness so much as a pause after Q2's 1.8% rise. ERA expects little new CCR supply until 2027, so the choice for now is mainly between the few recent launches and resale homes.
- Investors: the rental figures are the ones to watch. CCR rents dipped 0.3% and CCR vacancy, at 8.4%, is the highest of the three regions. Rental yields in prime districts depend heavily on the specific unit and tenant pool, so test your numbers conservatively.
- HDB upgraders: softer HDB resale prices can affect how much cash and CPF you free up from your flat. Get a realistic valuation of your flat before committing to a new launch.
- Comparing launches on psf: new launches are sized differently since GFA harmonisation, so psf prices are not always like-for-like. Our GFA harmonisation explainer walks through why.
It also helps to look beyond the CCR label. The price premium of prime homes over city-fringe homes has narrowed a lot, as this explainer on how close Bukit Timah and Upper Thomson pricing have become shows, which changes the value comparison for many buyers.
Where Dunearn House fits
Dunearn House was one of only two CCR launches in Q3. It sold 212 of its 380 homes on its July launch weekend at an average of S$3,140 psf, with launch prices from S$1.475M for a 2-bedroom, S$2.597M for a 3-bedroom and S$3.588M for a 4-bedroom. With ERA expecting no more CCR launches this year, it remains one of the few new 99-year leasehold options in Bukit Timah until the next Turf City projects arrive. See the latest Dunearn House prices and availability, or WhatsApp us on +65 8866 9422 to talk through the remaining units and how they compare with resale homes nearby.
This article is for general information only and is not financial or investment advice. Figures are as reported by the sources below at the time of writing and may change. Please do your own checks and seek professional advice before buying property.
Sources
- URA: Release of 3rd Quarter 2026 real estate statistics (23 October 2026)
- ERA Singapore: 3Q 2026 URA Private Residential Report: Prices Continue Growing Despite Quieter Quarter for New Home Sales (2 October 2026)
- Cushman & Wakefield: Comments on URA real estate statistics for Q3 2026 (26 October 2026)
- EdgeProp Singapore: Dunearn House sells 56% of units on launch weekend at average of $3,140 psf (26 July 2026)